IN PARTNERSHIP WITH
For more information visit: www.incisiveworks.com
This digital experience is an Incisive Works product © 2023 Incisive Business Media (IP) Limited
Real assets and the net-zero pathway
xxxxxxx
xxxxxxxxxxx
The sustainable forces driving change in real assets
The real asset green premium explained
hile conditions for fixed income markets were extremely tough in 2022, there were hopes that 2023 would be different. However, bond yields have
trended higher again in recent months and remain volatile, despite optimism that central banks’ hiking cycles are reaching their peaks. There may still be volatility ahead, but at today’s starting yield levels, which are historically strongly correlated with returns, there are promising opportunities for the discerning investor.
W
“Net zero commitments are set to revolutionise the world of long-dated real assets”
scroll
FIXED INCOME
Mark Meiklejon on the Aviva Investors’ Climate Transition Real Assets Fund
How can pension funds use ESG to futureproof portfolios?
Professional Investors Only
Featured in this Spotlight
Click on the plus icons for more information
Ketish Pothalingam Portfolio Manager, EVP
Ketish is a member of PIMCO’s ESG team, focusing on corporate credit and global bond ESG portfolios
Samuel Mary ESG Research Analyst, SVP
Samuel focuses on the integration of ESG factors into PIMCO's portfolio management and credit research
Sectors in focus: real estate, banking and more
Spotlight on: GIS Income Fund
'Bend but don't break': the portfolio view
Big picture outlook with Dan Ivascyn
Indeed, a major risk now is of missing out on the returns that could be on offer, whether by staying too heavily in equities or by being too comfortable in very safe government bonds.
"People are pretty happy right now because they’re getting so much yield on their government bonds. But if they go out just a little bit more in the risk spectrum, they can pick up several hundred basis points in yield"
There are promising opportunities in fixed income
Time to get on board?
Marketing Communication This is a marketing communication. This is not a contractually binding document and its issuance is not mandated under any law or regulation of the European Union or the United Kingdom. This marketing communication does not include sufficient detail to enable the recipient to make an informed investment decision. Please refer to the Prospectus of the UCITS and to the KIID before making any final investment decisions. For professional use only The services and products described in this communication are only available to professional clients as defined in the MiFiD II Directive 2014/65/EU Annex II Handbook and its implementation of local rules and as defined in the Financial Conduct Authority's Handbook. This communication is not a public offer and individual investors should not rely on this document. Opinion and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. We believe the information provided here is reliable, but do not warrant its accuracy or completeness. The views contained herein represent those of the authors and not necessarily those of PIMCO. Views and opinions may be subject to change without notice Additional Information/Documentation A Prospectus is available for PIMCO Funds and UCITS Key Investor Information Documents (KIIDs) (for UK investors) and Packaged retail and insurance-based investment products (PRIIPS) key information document (KIDs) are available for each share class of each the sub-funds of the Company. The Company’s Prospectus can be obtained from www.fundinfo.com and is available in English, French, German, Italian, Portuguese and Spanish. The KIIDs and KIDs can be obtained from www.fundinfo.com and are available in one of the official languages of each of the EU Member States into which each sub-fund has been notified for marketing under the Directive 2009/65/EC (the UCITS Directive). In addition, a summary of investor rights is available from http://www.pimco.com .The summary is available in English. The sub-funds of the Company are currently notified for marketing into a number of EU Member States under the UCITS Directive. PIMCO Global Advisors (Ireland) Limited can terminate such notifications for any share class and/or sub-fund of the Company at any time using the process contained in Article 93a of the UCITS Directive.” RISK Investing in the bond market is subject to risks, including market, interest rate, issuer, credit, inflation risk, and liquidity risk. The value of most bonds and bond strategies are impacted by changes in interest rates. Bonds and bond strategies with longer durations tend to be more sensitive and volatile than those with shorter durations; bond prices generally fall as interest rates rise, and low interest rate environments increase this risk. Reductions in bond counterparty capacity may contribute to decreased market liquidity and increased price volatility. Bond investments may be worth more or less than the original cost when redeemed. Commodities contain heightened risk, including market, political, regulatory and natural conditions, and may not be suitable for all investors. Currency rates may fluctuate significantly over short periods of time and may reduce the returns of a portfolio. Derivatives may involve certain costs and risks, such as liquidity, interest rate, market, credit, management and the risk that a position could not be closed when most advantageous. Investing in derivatives could lose more than the amount invested. Equities may decline in value due to both real and perceived general market, economic and industry conditions. Investing in foreign-denominated and/or -domiciled securities may involve heightened risk due to currency fluctuations, and economic and political risks, which may be enhanced in emerging markets. Sovereign securities are generally backed by the issuing government. Obligations of U.S. government agencies and authorities are supported by varying degrees, but are generally not backed by the full faith of the U.S. government. Portfolios that invest in such securities are not guaranteed and will fluctuate in value. High yield, lower-rated securities involve greater risk than higher rated securities; portfolios that invest in them may be subject to greater levels of credit and liquidity risk than portfolios that do not. Mortgage- and asset-backed securities may be sensitive to changes in interest rates, subject to early repayment risk, and while generally supported by a government, government-agency or private guarantor, there is no assurance that the guarantor will meet its obligations. Income from municipal bonds may be subject to state and local taxes and at times the alternative minimum tax. Swaps are a type of derivative; swaps are increasingly subject to central clearing and exchange-trading. Swaps that are not centrally cleared and exchange-traded may be less liquid than exchange-traded instruments. Inflation-linked bonds (ILBs) issued by a government are fixed income securities whose principal value is periodically adjusted according to the rate of inflation; ILBs decline in value when real interest rates rise. Treasury Inflation-Protected Securities (TIPS) are ILBs issued by the U.S. government. Certain U.S. government securities are backed by the full faith of the government. Obligations of U.S. government agencies and authorities are supported by varying degrees but are generally not backed by the full faith of the U.S. government. Portfolios that invest in such securities are not guaranteed and will fluctuate in value. Past performance does not predict future returns This material contains the current opinions of the manager and such opinions are subject to change without notice. This material has been distributed for informational purposes only and should not be considered as investment advice or a recommendation of any particular security, strategy or investment product. Information contained herein has been obtained from sources believed to be reliable, but not guaranteed. No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission. PIMCO Europe Ltd (Company No. 2604517, 11 Baker Street, London W1U 3AH, United Kingdom) is authorised and regulated by the Financial Conduct Authority (FCA) (12 Endeavour Square, London E20 1JN) in the UK. The services provided by PIMCO Europe Ltd are not available to retail investors, who should not rely on this communication but contact their financial adviser.
Resilience: the secular theme shaping the future
Marketing Communication Professional Investors Only
‘Stagnation’ – a mixed outlook for the UK
Two underappreciated sectors offering potential
Aiming high: don’t leave returns on the table
BROWSe OTHER CHAPTERS
READ THE FIRST ARTICLE >
Read on to hear our views on this challenge in the first chapter of this guide. We’ll then analyse two sectors with untapped potential, before assessing the outlook for the UK and outlining PIMCO’s approach to income investing.
Spotlight on: PIMCO’s balanced approach to income investing
MARKETING COMMUNICATION
Josh Anderson, PIMCO Portfolio Manager
SPOTLIGHT
MENU
HIDE X
now is of not allocating enough to fixed income.
quity-like returns from high quality bonds? Two years ago, that was a very far-fetched idea. Today, however, things are very different. Indeed, it is a measure of how much circumstances have changed that the greater risk
E
“The fund has consistently outperformed the IA Sterling Strategic Bond sector”
Investors risk missing out if they don’t take advantage of the opportunities on offer in fixed income
“The comparison that investors have to make is between the expected returns in fixed income, which have increased substantially, or those from equity markets, which haven’t to the same extent,” says Alfred Murata, Portfolio Manager of the PIMCO GIS Income Fund.
None of this is to say that the environment for fixed income is risk-free. There are still landmines out there that require a measured approach and a focus on resilience.
Aftershocks
“Putting it simplistically,” he explains, “if bonds are yielding 4% then it might be attractive to invest in equities if you think the expected return is going to be 8%. But if bonds are yielding around 7%, as they are now, then you ought to be looking at, say, 10 or 11% from equities. That sort of return is much harder to find.”
Fixed income investors also risk missing out if they only stick to the safest bonds, warns Josh Anderson, fellow PIMCO GIS Income Portfolio Manager.
Bonds are back, although risks persist
< PREVIOUS ARTICLE
NEXT ARTICLE >
“People are pretty happy right now because they’re getting so much yield on their government bonds,” he says, “but if they go out just a little bit more in the risk spectrum, they can pick up several hundred basis points in yield.
“I think there's an under-appreciation of how much potential total return and yield investors are going to give up by being in the safe government securities. Over a three or four-year period, staying very, very safe can add up to a lot of return left on the table.”
“In our minds, the impact of a lot of the rate moves hasn’t fully played out,” says Anderson. “Last year there was a huge shock to the bond market, and those reverberations are still going on. Particularly in commercial real estate, and in the credit markets, where we continue to see defaults.”
Or as Murata puts it: “We have higher yields today but we also have less support from central banks. That can lead to more volatility in the marketplace.”
That said, however, heightened volatility is not necessarily a bad thing. “That volatility could impact some investors negatively, but it could also provide tremendous opportunities,” he says.
In this sort of environment, PIMCO’s approach can come to the fore. The PIMCO GIS Income Fund seeks to find attractive, risk-adjusted opportunities that may potentially do well in a variety of conditions. “We call this philosophy ‘bend but don’t break’,” says Anderson. “This means there’s a dispersion of return outcomes but we’re targeting assets that are well placed to potentially perform in relative terms in different economic circumstances.”
Relative outperformance in a range of conditions
This approach has been vindicated in recent, challenging times. While nine out of the top 10 competitors by AUM in the strategic bond funds space posted negative returns over the past three years, PIMCO’s GIS Income Fund was the only one that managed to earn a positive return, albeit a modest one.
The fund has also consistently outperformed the IA Sterling Strategic Bond sector over a three-year time period.
We’ll take a closer look at the sectors it is targeting in the next chapter.
“Volatility could impact some investors negatively, but it could also provide tremendous opportunities”
Alfred Murata, Portfolio Manager
GIS Income fund vs. the top 10 competitors by AUM in the IA Sterling Strategic Bond sector
The PIMCO Income Fund provides superior three-year cumulative returns (%)
Share value can go up as well as down and any capital invested in the Fund may be at risk. The Fund may use derivatives for hedging or as part of its investment strategy which may involve certain costs and risks. For more details on the fund’s potential risks, please read the Key Investor Information Document. As of 30 September 2023. Drawdowns as from July 2018 to September 2023. Performance is shown for the Institutional, Income class, GBP shares, annualized and net of fees. SOURCE: PIMCO For illustrative purposes only. Past performance does not predict future returns. All periods longer than one year are annualised.
1.7%
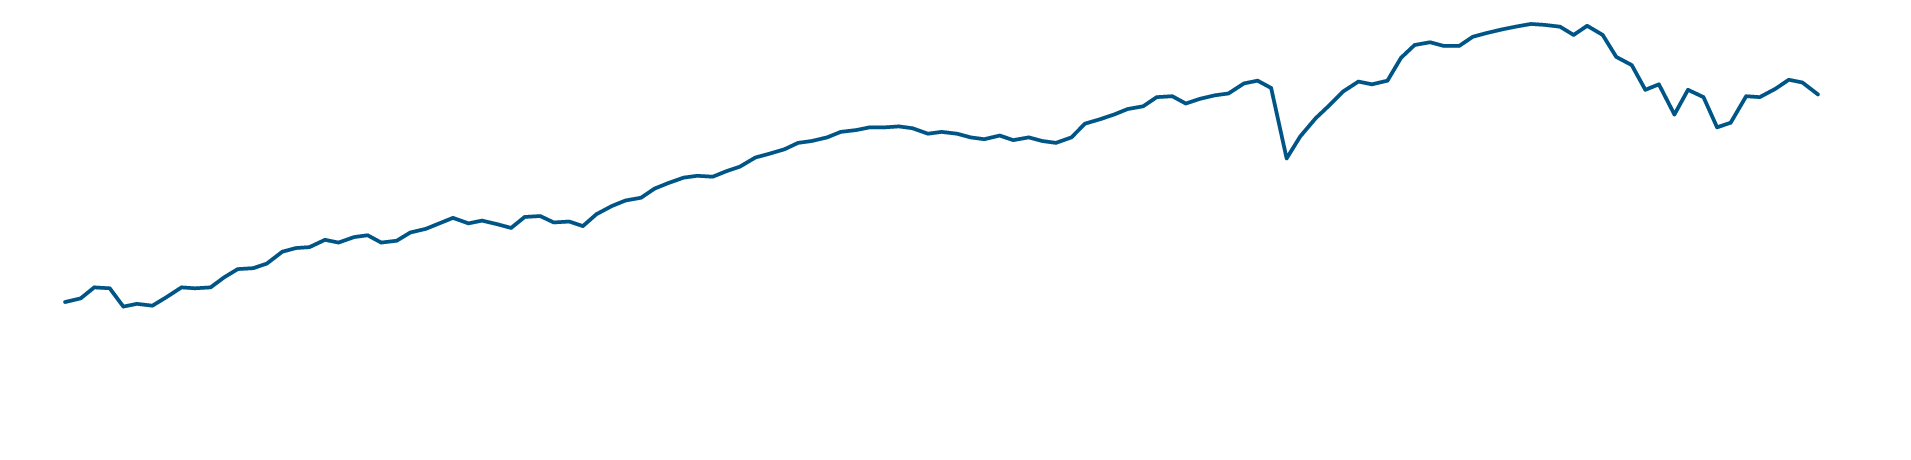
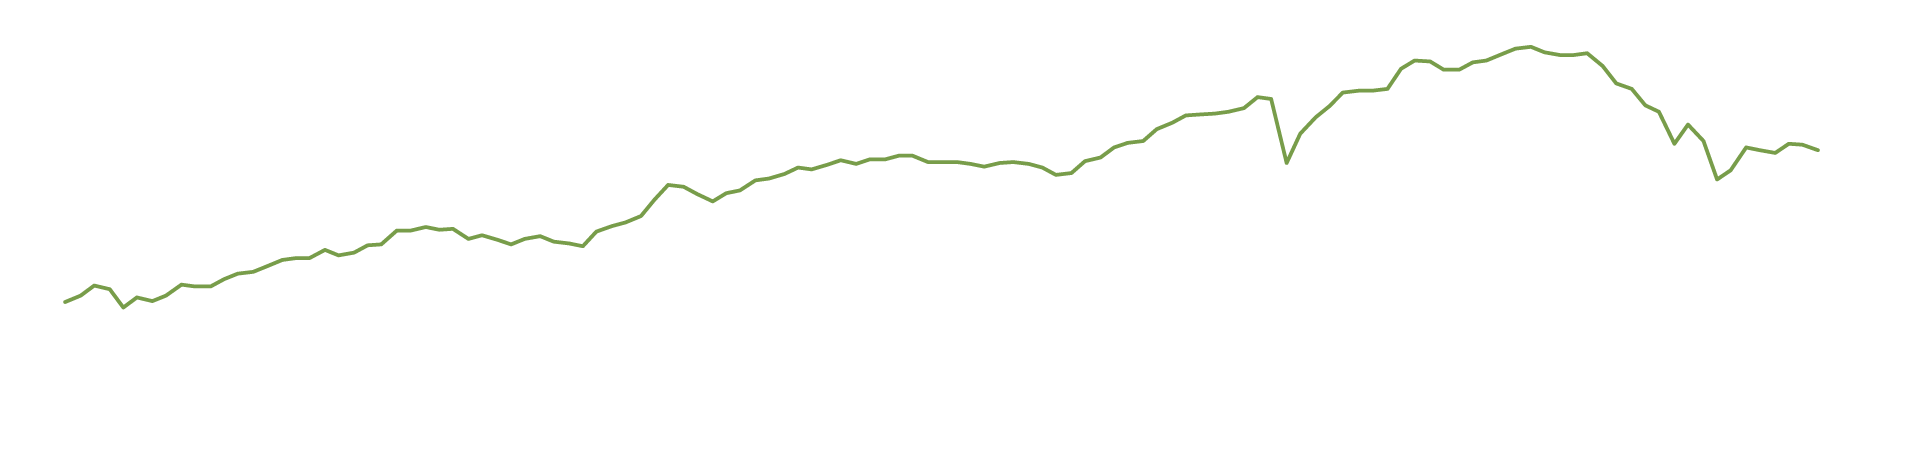
PIMCO’s GIS Income Fund has exhibited higher risk-adjusted returns and better downside protection than the IA Sterling Strategic Bond Sector
Growth of £100
As of 30 September 2023. Source: PIMCO, Morningstar. Performance is shown for the institutional class, GBP shares, annualized and net of fees. Past performance does not predict future returns. All investments involve risk including the possible loss of capital.
GIS Income (GBP-Hedged)
IA Sterling Strategic Bond
Sources.
(1) As of 30 September 2023. (2) There is no guarantee that the fund will achieve any forecasts or objectives as stated herein.
1
2
Banking and real estate look appealing as PIMCO’s GIS Income Fund seeks wider spreads with lower credit risk
Sustainable investment examples
PREV
NEXT
“In theory a bank could be taking these deposits, investing in short-term government bonds at a 5% or even higher yield, and yet be passing on close to zero to depositors.”
“Even with a 20% drop in housing, many of these securities can still be very well-protected”
Company B SECTOR: Packaging MATURITY: September 2028 COUNTRY OF DOMICILE: Ireland Green bond proceeds to be allocated towards expenditures relating to energy efficiency projects and manufacturing of sustainable packaging. PIMCO had a 1x1 call with the company to discuss best practices for ESG bond disclosure and reporting. We recommended that the company consider leveraging additional environmental indicators to quantify the environmental impacts of its sustainable aluminium products. PIMCO also shared guidance on sustainable bond issuance and examples of lifecycle impact assessments.
green bond
Company A SECTOR: Real estate finance MATURITY: 15 April 2031 COUNTRY OF DOMICILE: United States This bond focuses on energy efficiency, green buildings, infrastructure and renewable energy-generation projects. Following the issuance of the bond, PIMCO also engaged with the company to request the creation of a green bond framework to provide a deeper level of assurance to market participants. We suggested they include language regarding exclusionary categories given their investments in the natural gas value chain.
Company C SECTOR: Materials MATURITY: 15 January 2032 COUNTRY OF DOMICILE: United States The company’s second sustainability-linked bond (SLB) includes key performance indicators centred on reducing its industrial water-withdrawal intensity by the end of 2026 and increasing the representation of women in leadership positions to 30% or more by 2025. After passing up the opportunity to invest in the company's initial SLB in 2020, PIMCO met with management to discuss their ESG action plan and provide recommendations for improvement. Following our discussion, the company announced more ambitious ESG targets and issued this second SLB, where PIMCO participated.
sustainability-linked bond
1 / 3
2 / 3
3 / 3
Josh Anderson, Portfolio Manager
“Xxxxxxxxxxxx xxxxxx xxxx xx xxx xxx xxxx xxxxx xxxxxxxxxx xxxxxx xxxx xxx xxx xxxxx xxxxxx xxx xxxxxxx xxxx xxxxxxxxx xxxxxxx xxxx xxxxxxx”
Xxxxxx Xxxxxx, Xxxxxx
Sweet spots in real estate
though interest rates have been increased dramatically, many banks are not passing them along to depositors,” says Alfred Murata.
his year’s bank crises were certainly dramatic. But looking forward, PIMCO is confident that we are through the worst. A major reason for this is that higher interest rates should be supportive for the banks’ profitability. “Even
T
Putting aside the ethics of this from a depositor perspective, it adds up to a positive outlook for the banking sector. Yet at present, some investors aren’t grasping the opportunity. They’re being put off by the banks’ mark-to-market calculations, which are currently showing a loss due to investments the banks made when rates were low, such as securities or loans.
Murata argues it is a mistake to focus on this calculation and not the banks’ forward profitability. “I think that as time passes, the banks’ profitability could offset these losses, which in any case have not actually been realised,” he says. “And the lending facilities provided by the US Federal Reserve should hopefully tide the US banks over.”
Of course, there is still a need to be vigilant and cautious. As a result, the firm is focusing on senior debt from the larger, systemically important banks, as these are the most likely to potentially benefit from government support if they were to run into trouble.
The other key focus for the PIMCO GIS Income Fund at present is real estate. Indeed, Josh Anderson says the whole AAA and AA structured-product market is very attractive.
“Spreads are historically wide,” he says. “They’re anywhere from 50 to 100, maybe even 150 basis points wider than they were pre-Covid.
“One of the reasons for this is that the banks, particularly regional ones, haven’t been buying the AAA structured products that we buy due to their mark-to-market issues. Neither has the Federal Reserve in the US. That’s driving a portion of the spread widening and is beneficial for us.”
At this lower end of the risk spectrum, PIMCO believes that US agency mortgage-backed securities are particularly attractive given current valuations. The residential loans packaged within these bonds are guaranteed by government-sponsored enterprises such as Fannie Mae, Freddie Mac and Ginnie Mae, offering a great deal of risk protection.
“Real estate is one asset class that we think is particularly compelling today”, says Anderson. “It benefits from the fact that while the market technicals are poor, these securities can provide compelling value for the investor that has a longer-term holding period.”
That’s not to dismiss non-agency mortgage-backed securities, however, which PIMCO also sees as an important opportunity. “As an asset class we think it will be very resilient, even if you have a downturn in housing,” says Anderson.
“In the US,” he continues, “many of these securities have a loan-to-value ratio of less than 50%. So even with a 20% drop in housing, they can still be very well-protected.
“We're seeing similar opportunities in the UK as well. We think the residential space will be very well-protected even during a downturn in housing.”
As for the PIMCO GIS Income Fund’s overall positioning, Murata says it has upgraded to a neutral view on interest rate risk, compared to the cautious view of a couple of years ago.
Duration and credit risk positioning
“We’ve been adding duration to the portfolio,” he says. “With the significant repricing that's taken place, we think that there's a lot more value in US and UK duration.”
However, there are still enough reasons to retain some circumspection. “Although inflation is on a downward trend, there is still substantial risk that the next few inflation prints could be higher than expected,” says Murata. “If that were to occur, it's likely that central banks will end up being more hawkish than anticipated, and we could have a widening in credit spreads.
“Given that our mandate is to generate a consistent level of income while trying to protect against downside risk, we think that it makes sense to just have a neutral view on duration rather than a more elevated one.”
As for credit risk, Murata says the fund is relatively cautious. “So far the economy has still performed very well, despite the rise in rates,” he says. “But we think that as time passes – as interest rates continue to rise and funding costs continue to increase – that is going to put pressure on the economy.”
Nevertheless, there are still areas where the fund is looking to spot opportunities. “We're trying to find positions where spreads are at very wide levels but which we think are not going to have significant credit risk in a downside economic scenario.”
“Spreads are anywhere from 50 to 100, maybe even 150 basis points wider than they were pre-Covid”
Recessionary conditions would be bad news for many but could potentially mean attractive returns for fixed income markets and the PIMCO Select UK Income Bond Fund
Emerging markets
When we look at emerging markets from a global perspective, valuations look quite attractive. But emerging markets don’t tend to do very well when you have a significant central bank tightening cycle across the globe. There’s also a lot of idiosyncratic uncertainty with emerging markets, tied to US or Western friction with China, Chinese growth questions, uncertainty in Eastern Europe and various elections across Latin America.
The bottom line is that we think emerging markets will be a good diversifier for clients over the course of the next few years, but our exposure remains low. We have reduced our position over the course of the last year and our focus is almost entirely on the higher quality and more liquid segments of the emerging markets.
We have small emerging markets currency exposures and our bond exposures are almost always in sovereigns and quasi-sovereigns. We’re very hesitant to move into emerging market corporates, frontier markets and lower-rated segments in the emerging markets opportunity set.
Seek Yield and diversification via select exposures within emerging markets
Focus on higher quality and more liquid areas of the emerging markets. Mostly sovereign or quasi-sovereign positions, very limited exposure to corporates.
Scale positions small given the potential for volatility from idiosyncratic and geopolitical events.
Country breakdown (PBE)
As of 31 October 2022. Source: PIMCO. EM Index Product is exposure to the ICE CDX EM Index. "PBE" denotes "Percent Bond Exposure".
Developed markets
“Interest rates are expected to stay restrictive in the UK overall, but they may start falling at some point next year, which would raise bond values and allow holders to potentially benefit from capital appreciation. And even if interest rates don’t fall, we’d expect bonds to offer a degree of safety and a predictable income compared to equities.”
“Given how much fixed income has repriced,” he says, “if you have stagnation, a mild recession or modest growth, then you could do very well.
e expect economic stagnation and a mild recession over the coming year in the UK.” That may not be great for the UK as a whole, but as PIMCO’s Josh Anderson explains, it ought to be for fixed income markets.
The rates picture will of course be heavily influenced by the UK’s inflation trajectory. To date the UK has been lagging behind the US in getting inflation under control, but Alfred Murata, lead portfolio manager on the PIMCO Select UK Income Bond Fund, believes there is room for cautious optimism.
“In the US, the Fed raised rates aggressively and now inflation has come down dramatically,” he says. “This dynamic has taken longer to play out in the UK, but I think the Bank of England has now caught up.”
Murata adds that he now sees a steady fall in UK inflation over time. “Nothing dramatic,” he says, “but just a continued weakening over the coming year, given the modest economic environment that we expect.”
For the PIMCO Select UK Income Bond Fund, this represents an opportunity to add duration, says Murata. “As rates have been rising in the UK, and expectations for the Bank of England to continue to raise rates have as well, we've been adding some duration to the portfolio. Today I'd say we're cautiously positioned whereas before we were extremely cautiously positioned.”
The case for duration
Indeed, Murata says that as time passes, the case for adding duration in the UK should become more compelling. He’s also heartened by the fact that the UK has a much faster linkage between the rise in interest rates and the cost of mortgage debt than the US.
“In the US, many people have a 30-year fixed rate mortgage,” he says. “So even if the Federal Reserve raises rates, many people are not going to need to refinance their mortgage. In the UK, there's going to be a faster flow-through into the economy as a whole.”
The Fund is focusing on areas where spreads have widened significantly but the credit risk hasn’t increased substantially. One such area is UK residential mortgage-backed securities that are very seasoned, meaning the homeowners have built up sufficient equity to act as a buffer in the event of a housing dip.
“Over the past decade or so, we've seen continued liquidations from the UK asset resolution that took over the assets of some of the banks during the global financial crisis,” says Murata. For example, the mortgage assets of Northern Rock have been liquidated over time and that's provided a tremendous opportunity for us in the UK income portfolio.”
Central bank policy expected to stay restrictive
As of 30 September 2023. Source: Bloomberg, PIMCO The views and expectations expressed are those of PIMCO. There can be no guarantee that the trends mentioned above will continue. Statements concerning financial market trends are based on current market conditions, which will fluctuate.
Fed Funds Rate
BoE Base Rate
The path to disinflation is likely to remain bumpy
ECB Deposit Rate
Performance: PIMCO Select UK Income Bond Fund
As of 30 September 2023, subject to change. Source: PIMCO. *Benchmark: Bloomberg Sterling Agg 1-10yr Bond Index. The fund is actively managed in reference to the Bloomberg Sterling Agg 1-10yr Bond Index as further outlined in the prospectus and key investor information document. Duration based on PIMCO internal calculations. Past performance is not a guarantee or a reliable indicator of future results. All periods longer than one year are annualised.
Portfolio (before fees)
Benchmark
Institutional Class, Accumulation Shares
“
PIMCO SELECT FUNDS Past performance is not a guarantee or a reliable indicator of future results. PIMCO Select Funds plc is an umbrella type open-ended investment company with variable capital and with segregated liability between Funds incorporated with limited liability under the laws of Ireland with registered number 480045. The information is not for use within any country or with respect to any person(s) where such use could constitute a violation of the applicable law. The information contained in this communication is intended to supplement information contained in the prospectus for this Fund and must be read in conjunction therewith. Investors should consider the investment objectives, risks, charges and expenses of these Funds carefully before investing. This and other information is contained in the Fund's prospectus. Please read the prospectus carefully before you invest or send money. For additional information and/or a copy of the Fund's prospectus, please contact the Administrator: State Street Fund Services (Ireland) Limited, Telephone +353-1-776-0142, Fax +353-1-562-5517 Additional Information/Documentation A Prospectus is available for PIMCO Funds and Key Investor Information Documents (KIIDs) are available for each share class of each the sub-funds of the Company. The Company’s Prospectus can be obtained from www.fundinfo.com and is available in English, French, German, Italian, Portuguese and Spanish. The KIIDs can be obtained from www.fundinfo.com and are available in one of the official languages of each of the EU Member States into which each sub-fund has been notified for marketing under the Directive 2009/65/EC (the UCITS Directive). In addition, a summary of investor rights is available from www.pimco.com .The summary is available in English. The sub-funds of the Company are currently notified for marketing into a number of EU Member States under the UCITS Directive. PIMCO Global Advisors (Ireland) Limited can terminate such notifications for any share class and/or sub-fund of the Company at any time using the process contained in Article 93a of the UCITS Directive. RISKS Credit and Default Risk A decline in the financial health of an issuer of a fixed income security can lead to an inability or unwillingness to repay a loan or meet a contractual obligation. This could cause the value of its bonds to fall or become worthless. Funds with high exposures to non-investment grade securities have a higher exposure to this risk. Currency Risk changes in exchange rates may cause the value of the investments to decrease or increase. Derivatives and Counterparty Risk The use of certain derivatives could result in the fund having a greater or more volatile exposure to the underlying assets and an increased exposure to counterparty risk. This may expose the fund to larger gains or losses associated with market movements or in relation to a trade counterparty being unable to meet its obligations. Emerging Markets Risk Emerging markets, and especially frontier markets, generally carry greater political, legal, counterparty and operational risk. Investments in these markets may expose the fund to larger gains or losses. Interest Rate Risk Changes in interest rates will usually result in the values of bond and other debt instruments moving in the opposite direction (e.g. a rise in interest rates likely leads to fall in bond prices). Liquidity Risk Difficult market conditions could result in certain securities becoming hard to sell at a desired time and price. Mortgage Related and Other Asset Backed Securities Risks Mortgage or asset backed securities are subject to similar risks as other fixed income securities, and may also be subject to prepayment risk and higher levels of credit and liquidity risk. BENCHMARK Unless referenced in the prospectus and relevant key investor information document, a benchmark or index in this material is not used in the active management of the Fund, in particular for performance comparison purposes. Where referenced in the prospectus and relevant key investor information document a benchmark may be used as part of the active management of the Fund including, but not limited to, for duration measurement, as a benchmark which the Fund seeks to outperform, performance comparison purposes and/or relative VaR measurement. Any reference to an index or benchmark in this material, and which is not referenced in the prospectus and relevant key investor information document, is purely for illustrative or informational purposes (such as to provide general financial information or market context) and is not for performance comparison purposes. Please contact your PIMCO representative for further details. AAA (highest) to B, C, or D (lowest) for S&P, Moody’s, and Fitch respectively. CORRELATION As outlined under “Benchmark”, where [disclosed herein] and referenced in the prospectus and relevant key investor information document, a benchmark may be used as part of the active management of the Fund. In such instances, certain of the Fund’s securities may be components of and may have similar weightings to the benchmark and the Fund may from time to time show a high degree of correlation with the performance of any such benchmark. However the benchmark is not used to define the portfolio composition of the Fund and the Fund may be wholly invested in securities which are not constituents of the benchmark. Investors should note that a Fund may from time to time show a high degree of correlation with the performance of one or more financial indices not referenced in the prospectus and relevant key investor information document. Such correlation may be coincidental or may arise because any such financial index may be representative of the asset class, market sector or geographic location in which the Fund is invested or uses a similar investment methodology to that used in managing the Fund
PIMCO GIS INCOME FUND
Seek consistent income distribution as a driver of total returns over time
Benchmark-agnostic* allowing for a flexible, actively managed approach to invest across the $136 trillion bond market
Led by Group CIO Dan Ivascyn and Portfolio Managers Alfred Murata and Josh Anderson
As of 31 August 2023. Source: PIMCO. *The fund measures its performance against the Bloomberg US Aggregate Index (the “Index”). However, the fund does not track nor seeks to outperform the Index (or any other index). As a benchmark agnostic strategy, it instead focuses on generating high current income, irrespective of the performance or composition of the Index.
Balanced Approach
Flexibility
Award-winning PM Team
Investment process – Balance yield and capital preservation objectives
Manage portfolio risk and ensure it is truly diversified
Capital preservation
Yield
PIMCO’s macroeconomic views
PIMCO GIS INCOME FUND philosophy
We have extensive experience in managing income strategies and a successful track record of delivering consistent income and capital appreciation.
Expertise
Our multi-sector income strategy is actively managed in line with our macroeconomic views. The flexibility of our mandates helps us to navigate volatility.
Differentiated approach
The insights of our secular and cyclical investment forum process is informed by deep credit research
Rigorous investment process
Our global investment and risk management teams reach across multiple sectors and geographies. We have more than 200 portfolio managers around the world, all coming up with ideas to include in our portfolios. And our Global Advisory Board includes experts such as Mark Carney and Ben Bernanke.
Extensive resources
Source: PIMCO
Leverages PIMCO’s robust "top down" and "bottom up" analytics across sectors along with our scale and relationships across global fixed income markets
PIMCO’s Fixed Income Expertise
Source: PIMCO For illustrative purposes only.
Allocate to high quality securities that should perform well during an economic slowdown and higher yielding securities that should remain resilient even in negative economic scenarios.
Seek to hedge against heightened volatility
Seek high and consistent level of distribution
income-oriented strategies from PIMCO
GIS Income Fund
Strategy since March 2007 UCITS fund since Nov 2012
SOURCE: PIMCO. * It refers to the Institutional EUR Hedged share class.
February 2011
UK Income Bond
Benefits from the full global opportunity set
Core allocation to Sterling securities with up to one-third globally sourced income
Seek consistent income & potential capital appreciation over time
Share value can go up as well as down and any capital invested in the Fund may be at risk. The Fund may use derivatives for hedging or as part of its investment strategy which may involve certain costs and risks. For more details on the fund’s potential risks, please read the Key Investor Information Document
Reflect PIMCO’s top-down views & include best income generating ideas
Mitigate downside risk by including high quality assets alongside higher income assets
Inception
Regional focus
Key features
Risk
TWO income-oriented strategies
Access multiple sources of return
Click on a fund name to view that fund and hover over boxes for details
As of 31 August 2023. Source: PIMCO Past performance is not a guarantee or a reliable indicator of future results and no guarantee is being made that similar returns will be achieved in the future. Dividend is not guaranteed.
Focus on income as a driver of total return
Seek to reduce downside risk versus other credit-oriented strategies
Strong consistent return since inception
Diversifying allocation within investor portfolios
Risk management
Duration: 0 to + 8 years Corporate high yield: Max 50% Emerging markets: Max 20% Currency: Max 30% gross exposure
Seeks a consistent income distribution + capital appreciation with volatility slightly higher than core bonds A consistent income distribution helps portfolio build up returns over time
Successful track record navigating rising interest rate environments Delivered attractive risk-adjusted returns of 5.4% (after fees) since inception Dan Ivascyn and Alfred Murata were named Morningstar Fixed Income Managers of the Year for 2013
Fixed Income continues to be a source of liquidity, carry and diversification Current macro backdrop and our secular thesis suggest the flexibility of the Income approach may be especially valuable in the environment ahead
Utilise a “bend but don’t break” philosophy where we expect price volatility, but we attempt to avoid permanent losses This has resulted in less volatility historically than other credit-oriented strategies
Income and capital objectives
Strategy: the best ideas and dynamic sector weightings
Key guidelines: duration and credit
Risk management: staying aware of the potential risks
This fund seeks to provide a high and consistent level of current income with a secondary objective of achieving long-term capital appreciation with a focus on UK opportunities
PIMCO's best ideas across multiple fixed income sectors Two-thirds of the portfolio invested in sterling denominated securities Sector weightings dynamically managed, in line with PIMCO’s broader investment outlook
Average duration range: 1-8 years Below investment grade: Max 50% Emerging market bond securities: Max 25%
Spotlight on: PIMCO’s approach to income investing
Hover over boxes for more details
PIMCO GIS Income Fund
Benchmark-agnostic strategy with flexibility to access global opportunity set
PIMCO Select UK Income Bond Fund